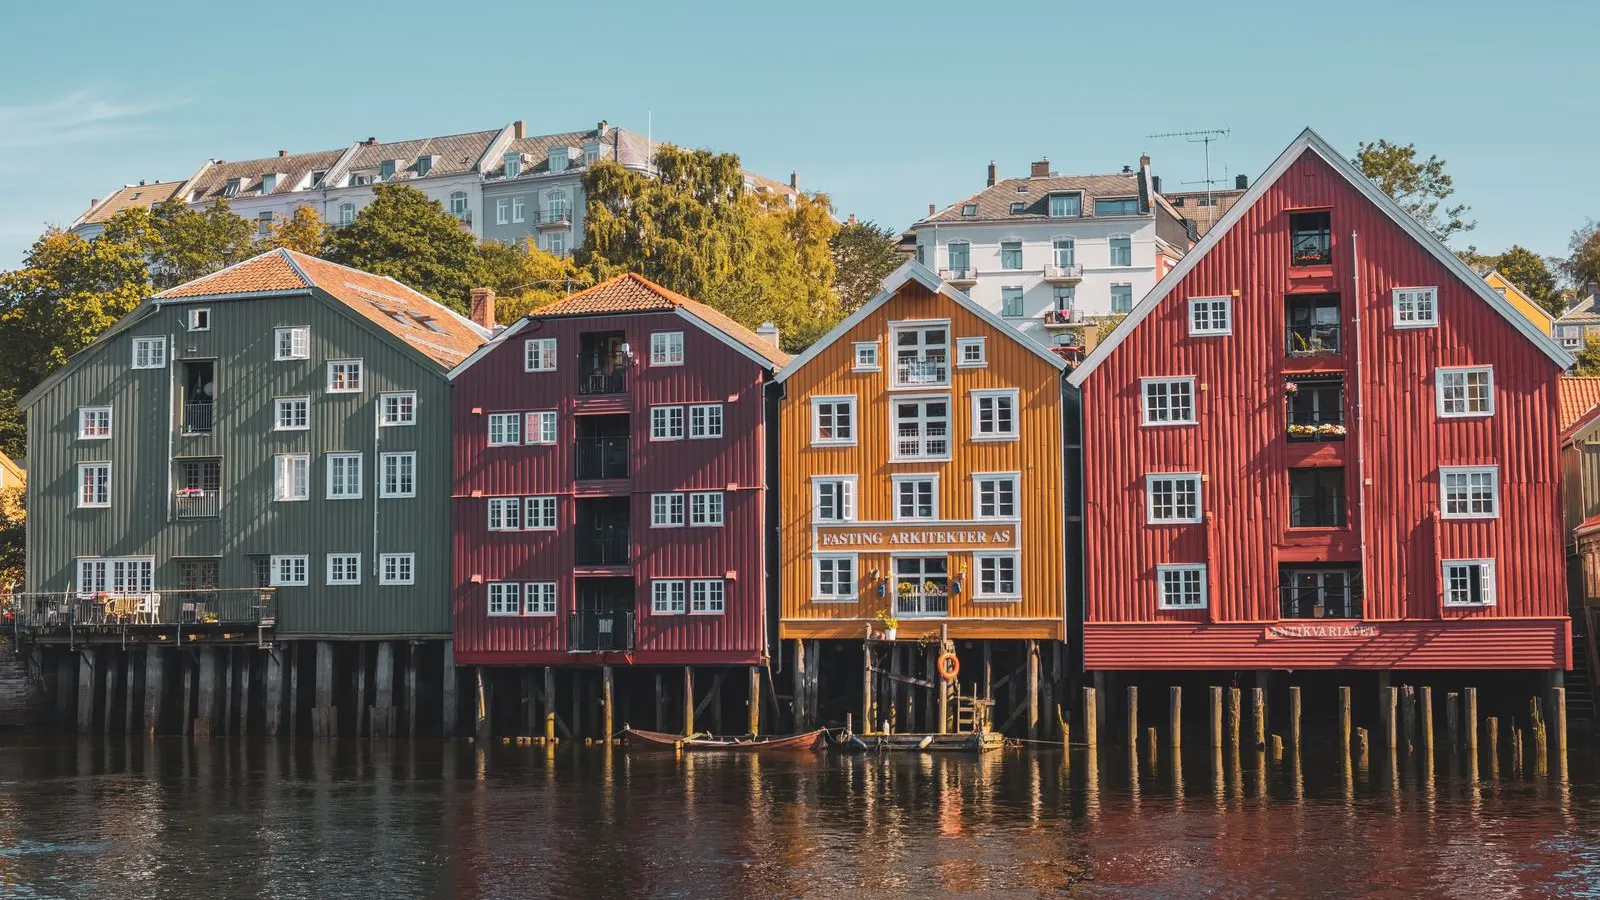
Is it cheaper to live in Norway or the UK? There is no reliable answer that applies to every household. Norway is a high-price country, and everyday purchases can feel expensive to a visitor paying in pounds. Yet the cost of a particular home, commuting pattern, childcare arrangement and income can change the result considerably.
If you are researching property Norway options, compare an actual Norwegian lifestyle with your actual UK one. A family leaving a costly London rental has a different calculation from a mortgage-free couple in a small British town. This guide explains how to make a useful comparison without relying on an unsupported claim that one entire country is a fixed percentage cheaper.
THE SHORT ANSWER: COMPARE WHAT YOU KEEP
The useful question is not simply where groceries cost less. It is how much money remains after tax, housing, transport, family needs and essential saving. A higher salary does not guarantee a better outcome if it brings a more expensive home or a second car. Equally, a costly restaurant meal does not tell you whether a household’s overall budget works.
Build both budgets in their local currencies first. Use your expected Norwegian net income and realistic Norwegian costs, then compare the outcome with your UK position. If your income remains in pounds, exchange rates become part of ordinary household risk. Keep this distinction clear: a person earning and spending in NOK has a different exposure from someone funding a Norwegian home from British savings.
WHAT OFFICIAL PRICE DATA CAN TELL YOU
Statistics Norway’s European price-level comparison reports Norway’s household consumption price level at 128.6 in its preliminary 2025 figures, with the EU average set to 100. That shows Norway’s high overall price level relative to that benchmark. It does not mean Norway is 28.6% more expensive than the UK.
The same published table does not provide a UK value for that period. It therefore cannot support a direct percentage gap between the two countries. Also distinguish inflation from price levels: inflation measures changes over time within a country, while a price-level comparison considers relative costs across countries. Neither gives a complete personal moving budget on its own.
HOUSING IS USUALLY THE DECIDING FACTOR
Housing can outweigh smaller savings across many everyday purchases. Compare properties with similar usable space, condition, access and travel times. Oslo should not stand for all Norway, just as central London should not stand for the whole UK. A mountain home also needs a different comparison from a city apartment near an employer.
If buying, include finance costs, maintenance, insurance, municipal charges and any communal payments or shared debt. If renting, establish what the rent includes and what you pay separately. Do not compare UK mortgage repayments with Norwegian rent as if they were equivalent measures. Our guide to Norwegian house prices and purchase budgets explains how to look beyond the asking price.
FOOD SHOPPING AND EVERYDAY SPENDING
Groceries deserve a line-by-line check because households buy very different baskets. Compare your normal food, not a tourist’s week of convenience meals. Cooking at home, choosing seasonal items and shopping around can make a meaningful difference. Imported preferences may cost more, while a change in routine may reduce spending without feeling like a sacrifice.
Statistics Norway’s preliminary 2025 comparison places food and non-alcoholic beverages at 133.1 against an EU average of 100. Again, that is not a direct UK comparison. Use the evidence as a reason to budget carefully, then price your own weekly basket. Include cleaning products, toiletries and occasional household purchases rather than counting food alone.
EATING OUT AND THE HOLIDAY EFFECT
A holiday can give a distorted impression of living costs. Visitors often eat out, hire transport and pay short-stay accommodation rates. Residents may cook, use season tickets and spread durable purchases over several years. Repeating a holiday budget for twelve months is not a fair estimate of normal life.
Nevertheless, restaurant habits matter. If regular meals out and drinks are important to you, include them honestly rather than assuming you will stop after moving. The same applies to ski passes, gym memberships and cultural events. An affordable plan should support the life you genuinely want, not an idealised routine that only works because every enjoyable activity has been removed.
HEATING, ELECTRICITY AND HOME CONDITION
Norwegian housing costs depend on the building as well as the climate. Size, insulation, heating equipment, occupancy and location all affect consumption. Ask for actual historical energy use where available and understand whether it reflects full-time living or occasional holidays. An apparently modest bill from a lightly used cabin is not evidence of low year-round costs.
Compare the total energy bill, including relevant network charges and other components, rather than a headline unit price. Policies and support schemes can change, so confirm what applies to the property and your eligibility. Add a maintenance reserve for heating systems and the building fabric. Efficiency improvements may be worthwhile, but obtain costs before assuming they will quickly pay for themselves.
USE A RESEARCHED HOUSEHOLD BUDGET
For a constructive starting point, OsloMet’s SIFO reference budget sets out examples of ordinary consumer expenditure for different households. It includes current spending and provision for less frequent purchases. It is a research-based example of an acceptable consumption level, not a claim about what every family spends.
Importantly, it excludes housing, electricity and several other costs, including holiday travel and some health spending. Add those separately. Do not present a SIFO total as the full amount needed to live in Norway. Its main value is helping you remember categories and adjust them for your household, rather than providing a single number that ends the discussion.
TRANSPORT: THE COST OF YOUR LOCATION
A home near work and public transport may reduce the need for a car. A more remote home may offer space and scenery but add driving, parking and winter travel. Compare the whole transport pattern: commuting, school runs, shopping, visiting friends and airport connections. A cheap property can become less economical if every ordinary journey is difficult.
If you need a car, consider purchase or finance, insurance, servicing, tyres, energy or fuel, parking and tolls where applicable. Do not assume electric driving removes all those costs. For a holiday home, compare repeated car hire with ownership and paid transfers. The right solution depends on how often you visit and what you do once you arrive.
INCOME, TAX AND WORKING ARRANGEMENTS
Compare take-home income, not gross salary converted at today’s exchange rate. Tax residence, deductions, social security and the treatment of overseas income require professional advice. A dual-income household should also consider how long it may take the second adult to find suitable work. A budget based on two immediate salaries can be fragile.
Working remotely for a UK employer is not simply a financial choice. Immigration permission, employer obligations and tax can all matter. Our guide to moving to Norway as a UK citizen explains why you should settle the right to live and work before choosing a home around that assumption. Property ownership does not create those rights.
CHILDREN, HEALTHCARE AND FAMILY NEEDS
Childcare, school arrangements and healthcare can change a family’s comparison. Confirm current local fees, eligibility, availability and waiting arrangements. A national description of public services does not establish your household’s exact entitlement or the date it begins. Include after-school care, activities, meals and transport where relevant.
For healthcare, check how registration and coverage work for your circumstances, and allow for costs outside the services you can access. Do not assume that all treatment, dentistry or private care is free. A household with specific health, learning or access needs should research those early. The cheapest home on paper may be a poor choice if essential services are far away.
A SIMPLE WAY TO COMPARE TWO BUDGETS
Make two columns: your current UK household and the proposed Norwegian household. In each, list monthly net income, housing, energy, food, transport, childcare, insurance, communications, leisure and saving. Then add annual bills divided by twelve. This captures expenses that otherwise disappear from a casual monthly comparison.
Use three scenarios: expected costs, higher essential costs and a temporary income gap. For example, test whether the plan still works if only one adult earns at first. These are planning scenarios, not forecasts. Keep one-off moving costs separate from ongoing expenditure, so the first year’s removal bill does not get mistaken for the normal long-term monthly cost.
SECOND HOMES NEED A DIFFERENT CALCULATION
If you keep your UK home and buy a Norwegian holiday base, you are adding a second set of costs rather than swapping one household for another. Include flights, transfers, local management, insurance and maintenance during vacant periods. A property can be enjoyable without being the cheapest possible way to take a holiday, but the budget should acknowledge that openly.
If you hope to offset costs by letting, check the legal and building rules first. Base affordability on cautious net income after management, cleaning, utilities, vacancies and tax. Do not treat a busy ski week as evidence of year-round demand. Read our guide to buying Norwegian property as a foreigner before turning a holiday idea into a purchase plan.
WHERE NORWAY MAY FEEL LIKE BETTER VALUE
Value is not identical to low prices. A household may willingly spend more for access to nature, a useful layout, a shorter commute or a setting it enjoys throughout the year. Another household may find that keeping established work, family support and housing in Britain is financially and practically better. Both conclusions can be reasonable.
The strongest comparison identifies what changes in your own routine. Would you use nearby trails rather than pay for frequent trips? Would a bigger home create higher heating and maintenance bills? Would regular travel to relatives erase savings elsewhere? Write down those trade-offs. A realistic decision is more durable than a broad statement that Norway is either prohibitively expensive or surprisingly cheap.
TURN YOUR BUDGET INTO A PROPERTY BRIEF
Before deciding, consider a trial stay that resembles daily life. Shop where residents shop, travel at commuting times and spend a few evenings at home. Keep the receipts and record costs that would continue after a move. This is more useful than asking whether one memorable meal or taxi journey was expensive. It also shows which parts of the local lifestyle you would actually use.
Remember the cost of maintaining relationships in Britain. Regular flights, school-holiday travel and accommodation during visits can become important annual expenses. A household can feel comfortable month to month while still being surprised by those larger bills. Divide them into a monthly saving amount so they are funded before you book. The same approach works for appliance replacement and future home repairs.
Once the household numbers work, set a purchase budget that leaves room for transaction costs and reserves. Define the location, space and transport you need. Keep permanent relocation and holiday ownership as separate briefs unless you have checked that one property can legally and practically serve both purposes.
Explore our Norwegian property selection with those priorities in mind. To discuss a suitable mountain home or ski apartment, send a property enquiry with your budget and preferred lifestyle. Tell us whether you plan to relocate or visit, how many people will use the home and which costs concern you most. Clear information helps turn a general affordability question into a focused search.
SOURCES AND COMPARISON LIMITS
Researched in November 2026 using Statistics Norway’s European price-level statistics and OsloMet’s 2026 SIFO budget guidance. The cited 2025 price-level figures are preliminary; the published table has no equivalent UK value for that period. No direct country percentage or universal monthly budget is claimed. This is general planning information, not individual tax, financial or immigration advice.
Keep exploring.